

I live in a townhome with a flat roof, and it leaked after every storm for seven years. The insurance company deemed it normal wear and tear and denied the claim, and the threat of a lawsuit against the former owners for non-disclosure went nowhere.
I’ve always loved the rain, but during those years it only sparked increasing stress and alarm. A steady drip of contractors recommended various fixes. They cut a trap door in the rooftop deck and slathered every visible seam with tar. Replaced and widened the downspout. Patched the exterior stucco and resealed around the third floor windows.
Water kept getting in.
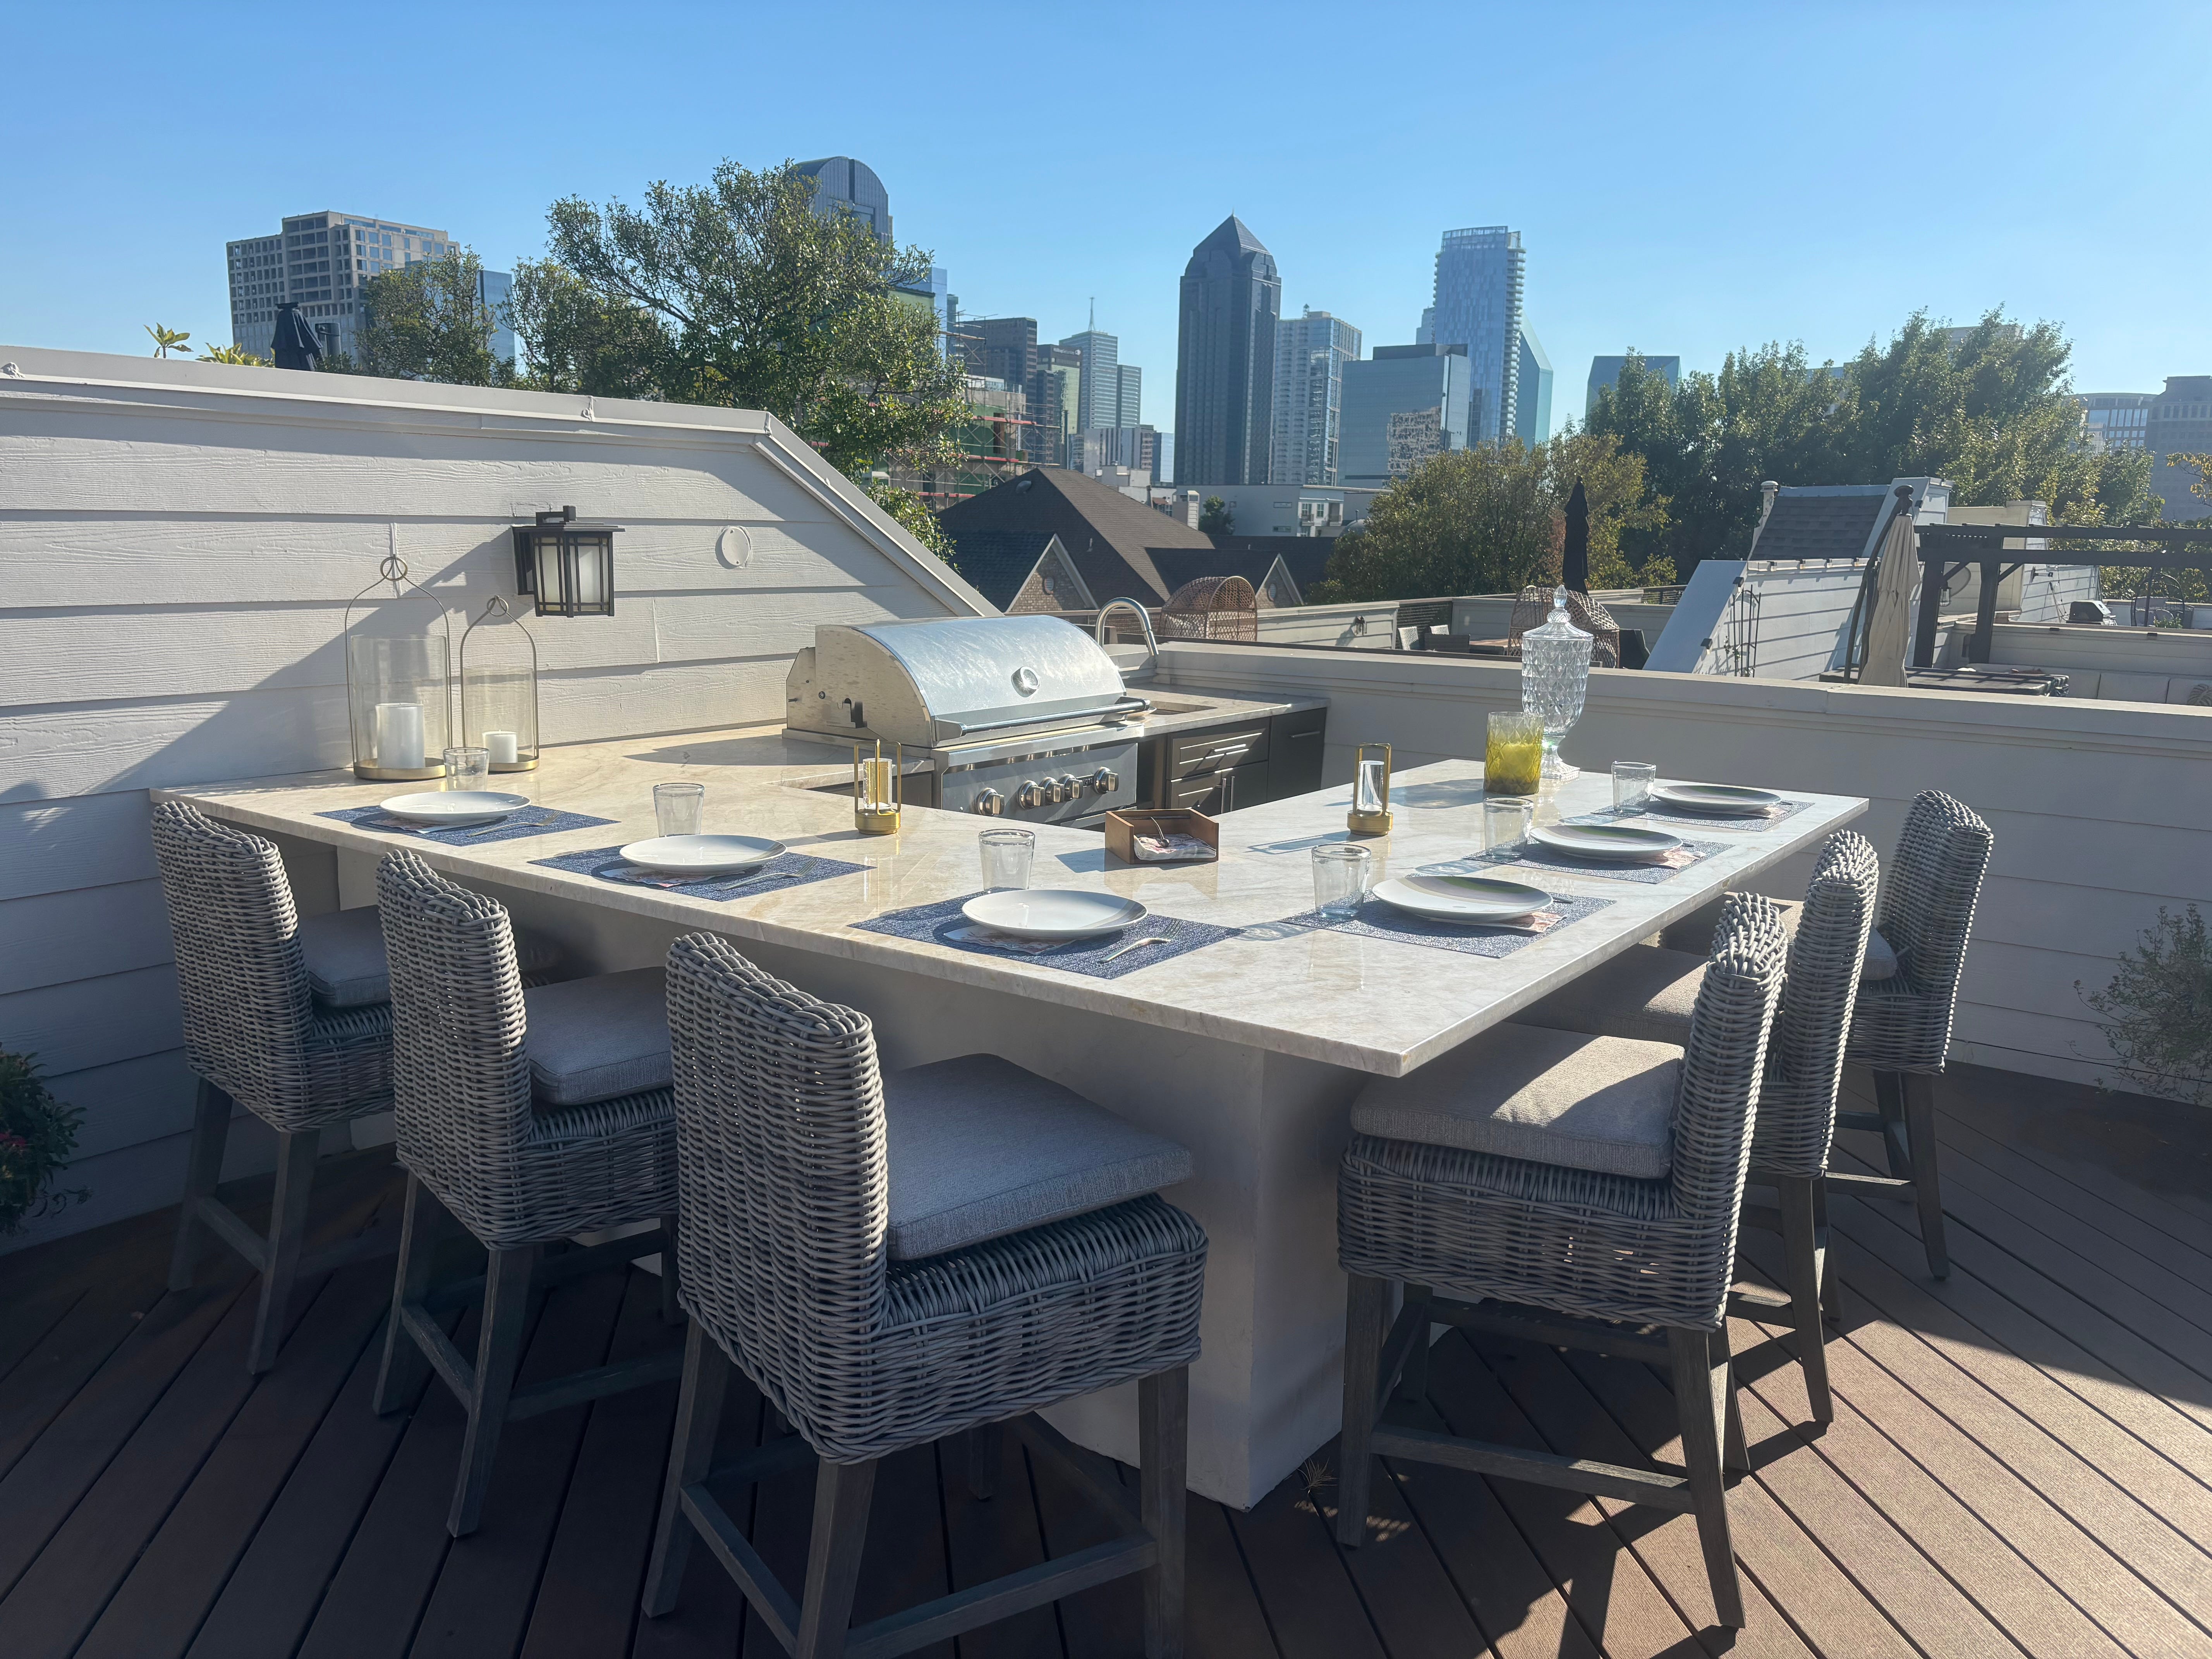
I finally bit the bullet and paid $70,250 for a new roof and rooftop deck. I also paid $60,600 to (re)construct an outdoor kitchen, fire pit, and planters on top. This does not include the cost of appliances, furniture, or plants, and I appreciate your understanding as I decline to calculate those sums at this time.
It took months of contractors invading my home and bothering my neighbors, and the stress prompted the cats to abandon their litter box in favor of ruining a leather couch. I also had to replace a perfectly functioning HVAC unit early after the roofers accidentally broke the line (which required renting a crane).
The end result was beautiful though. Worth it even, I thought with a sigh as I gazed out over the Dallas skyline.
When I noticed a familiar wet ceiling in the laundry room after a storm a few months later - this time ringed by a new dark cloud of mold - I briefly considered burning the whole place to the ground.
There are lots of ways people envision what it means to have wealth.
Time freedom.
Excess cash flow.
Ultimate flexibility.
Low fixed costs.
A sense of control and security / a lack of anxiety, especially around financial matters
You know what’s reliably incompatible with all those things on at least a semi-regular basis? Real estate.
The Good
It’s true that over time - over the very long term usually - owning a home might help you build wealth. Residential real estate in the U.S. has historically appreciated just over 4% annually. Despite rare dips (the Great Recession) and spikes (Covid), that average is fairly consistent and hovers at about a half a point above inflation1.
Those relatively low returns can be enhanced with leverage. Using debt increases investment risk, but access to cheap, long-term, fixed-rate mortgages is basically the entire reason real estate in an appealing asset class in America.
If you put $50K down on a $250K home and it rises 4% ($10K), you’ve actually earned 20% on your down payment.
The numbers are compelling, but they don’t include the often larger monthly cost of owning - and that’s before factoring in the impulse to buy more house than you would rent or the compulsion to increase spending on furniture, cars, decor, and even pets that is bestowed by mysterious forces once you’re graced with the title of homeowner.
Your rent payment is the maximum amount you’ll pay for housing; your monthly mortgage payment is just the beginning.
Overall, real estate is a good inflation hedge and diversifier, and it sometimes even offers a bit of a tax break2. A mortgage also doubles as a forced savings mechanism (once you get past the point in the amortization schedule where a meaningful chunk of your payment is going to principal).
If you buy a good home in a good area, you will almost certainly build equity over the long term.
The Bad
But it’s not automatic, and the opportunity costs are large. Owning real estate requires big investments - up front and on an ongoing and hard to predict basis - of both time and capital.
Instead of building a side hustle, say hello to Saturdays wandering through Home Depot trying not to look lost and panicked - and then trying to look lost and panicked so someone might take pity and help you. (I cannot tell you how many times I’ve cried at Home Depot.)
Sundays are reserved for mowing lawns and searching YouTube for things like “how to DIY install a ceiling fan without getting electrocuted.”
Or if you’re like me and enjoy paying full retail price to outsource any and all home maintenance, you can miss work meetings and social events on a regular basis to chit chat with internet strangers while they track dirt around your house.
Then there are the big cash outlays - “necessary capital expenditures” if you want to be adult about it. These fun “improvements” involve handing over years worth of savings for invisible things like a new hot water heater or plumbing line. You must blindly trust the salesperson who insists you really must repair the foundation or rewire the electrical system.
If you’re lucky these professionals will be competent, show up within a few hours of your appointment time, and pretend to overlook your distinct lack of knowledge and negotiating leverage when running quotes.
Sometimes you get to spend all your savings and then some on pretty improvements you can at least discern - a shiny new fridge that inexplicably talks to you or a basic guest bath refresh that costs more than your car.
And don’t forget landscaping. How can they get away with charging thousands of dollars for a few small bushes? Do I have to replace it after every heat wave and freeze? Why am I participating in this ecological farce??
Anything for some semblance of nature to break up our sprawling concrete jungles, I guess.
You can get rich enough to solve for the time / money suck of owning property, but the low grade background stress of the next looming crisis is insidious.
And you just know it’ll strike the weekend of your annual holiday party, when your in-laws are visiting, or while you’re on vacation.
Owning real estate is to exist in a never-ending maintenance cycle: preparation (saving), readiness (be on alert for any issues), action (tackle issues proactively if you want to be smart), and blissful completion (recovery from project trauma).
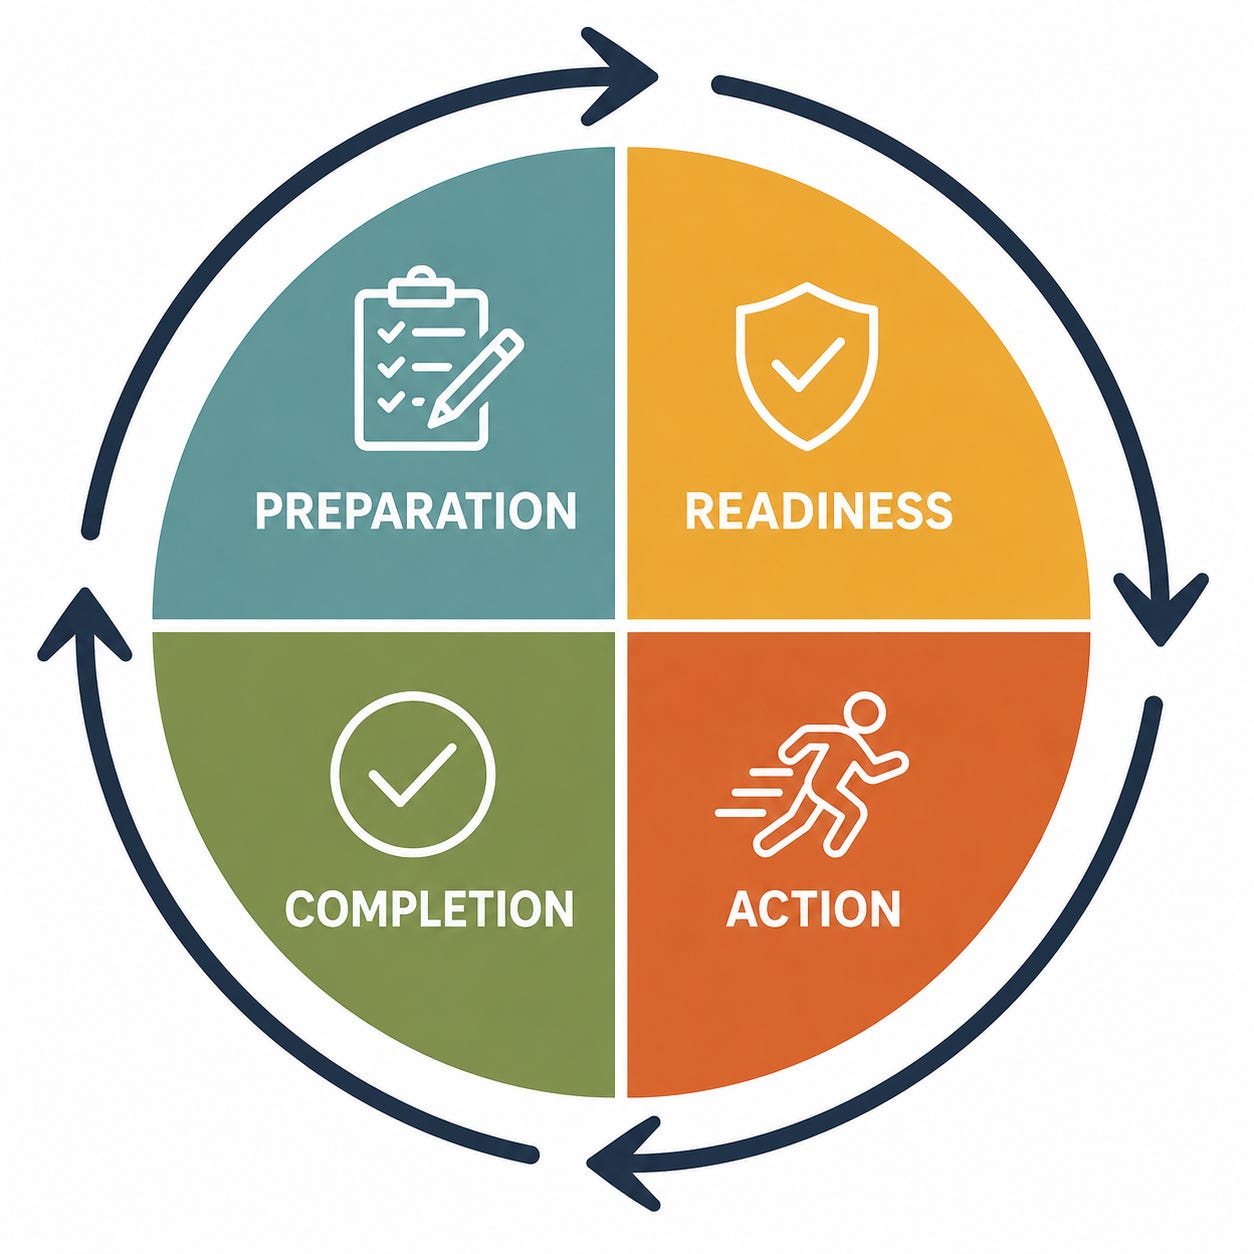
Which is all to say that even when it works - when the investment pays off and the risks are avoided and you build a ton of equity along the way - don’t be surprised if owning home doesn’t make you feel wealthy.
Real estate is tangible but inaccessible; it’s the definition of an illiquid asset. Owning property is a predictable path to feeling broke even as your net worth grows on paper.
This is what it means to be house-poor.
The Ugly
Real estate comes with concentrated risks that are difficult to fully mitigate.
Having a large portion of your net worth in any single asset is inherently risky, even more so when it’s tied to one location and economy. Few people are wealthy enough to own enough property to truly diversify within the asset class.
Despite your best maintenance efforts, your home value is largely at the mercy of your neighbors. Unemployment, blight, and crime can spread quickly during recessions and damage the economic value of neighborhoods and even whole cities.
Climate change is real, and natural disasters are becoming more common and catastrophic. As a result, insurance companies are increasingly unreliable. Many have pulled out of covering areas at higher risk of wildfires and hurricanes altogether. Where policies are available, deductibles and premiums are soaring.
Even worse, many homeowners find out their expensive coverage is worthless when they need it. The five largest home insurers collectively denied payment on nearly half of all claims made in 2025.3
The Verdict
Real estate can be a great investment, but it’s not the end all be all when it comes to building wealth. You don’t need to be in a rush to buy or wallow in FOMO if you’re renting.
There are a lot of upsides to renting, and flexibility is most sorely underrated. When you can move easily, you can make desirable life changes much more readily.
Growth = Change, and owning real estate is anathema to change. Too many people stay stuck and stagnant in their job, town, or relationship due to the legally binding nature of owning property.
Of course, there is plenty of upside to buying. The 65% of Americans who own their homes aren’t all masochists. Owners are more protected from the sting of inflation, and a paid off house makes retirement planning much simpler. Homes can eventually fund long term care, reducing the need to insure or save for that directly.
Buying real estate isn’t just a financial decision. Becoming a homeowner can engender lots of strong positive emotions: a sense of community, stability, pride, and achievement - especially in America where owning your home is a goal generally assigned at birth.
Feelings matter, and having a sense of place and a home to call your own is powerful.
If you want to feel financially free though, in the literal sense of having more money available than expenses on your priority list, buying an enormous depreciating asset that needs constant maintenance is not the most direct route.
You’re usually better off investing in the stock market4.
Just ask my ex who took his share of home equity in the form of VTSAX in our divorce just over two years ago. His holding is up 52% over that period.
My home value? Flat.5
When I called my contractor spiraling after I discovered the ongoing leak underneath six figures of new improvements, he talked me off the ledge like a reassuring father. Allegedly, he claimed, any home problem can be fixed.
I doubted it, but I had no choice but to persevere. There was no way out without committing fraud. I accepted my fate: trapped in a leaky, moldy house for the duration of my natural life.
After a half dozen more appointments and a brief spat between him and the roofer, it was determined that I simply needed the exterior rooftop door replaced all along; it had never been properly sealed.
It was a relatively easy fix, and as a treat for my mental health I decided to believe them when they said the brown spots weren’t mold. I haven’t had a leak in over three years, and I’ve been luxuriating complacently without any major issues since then.
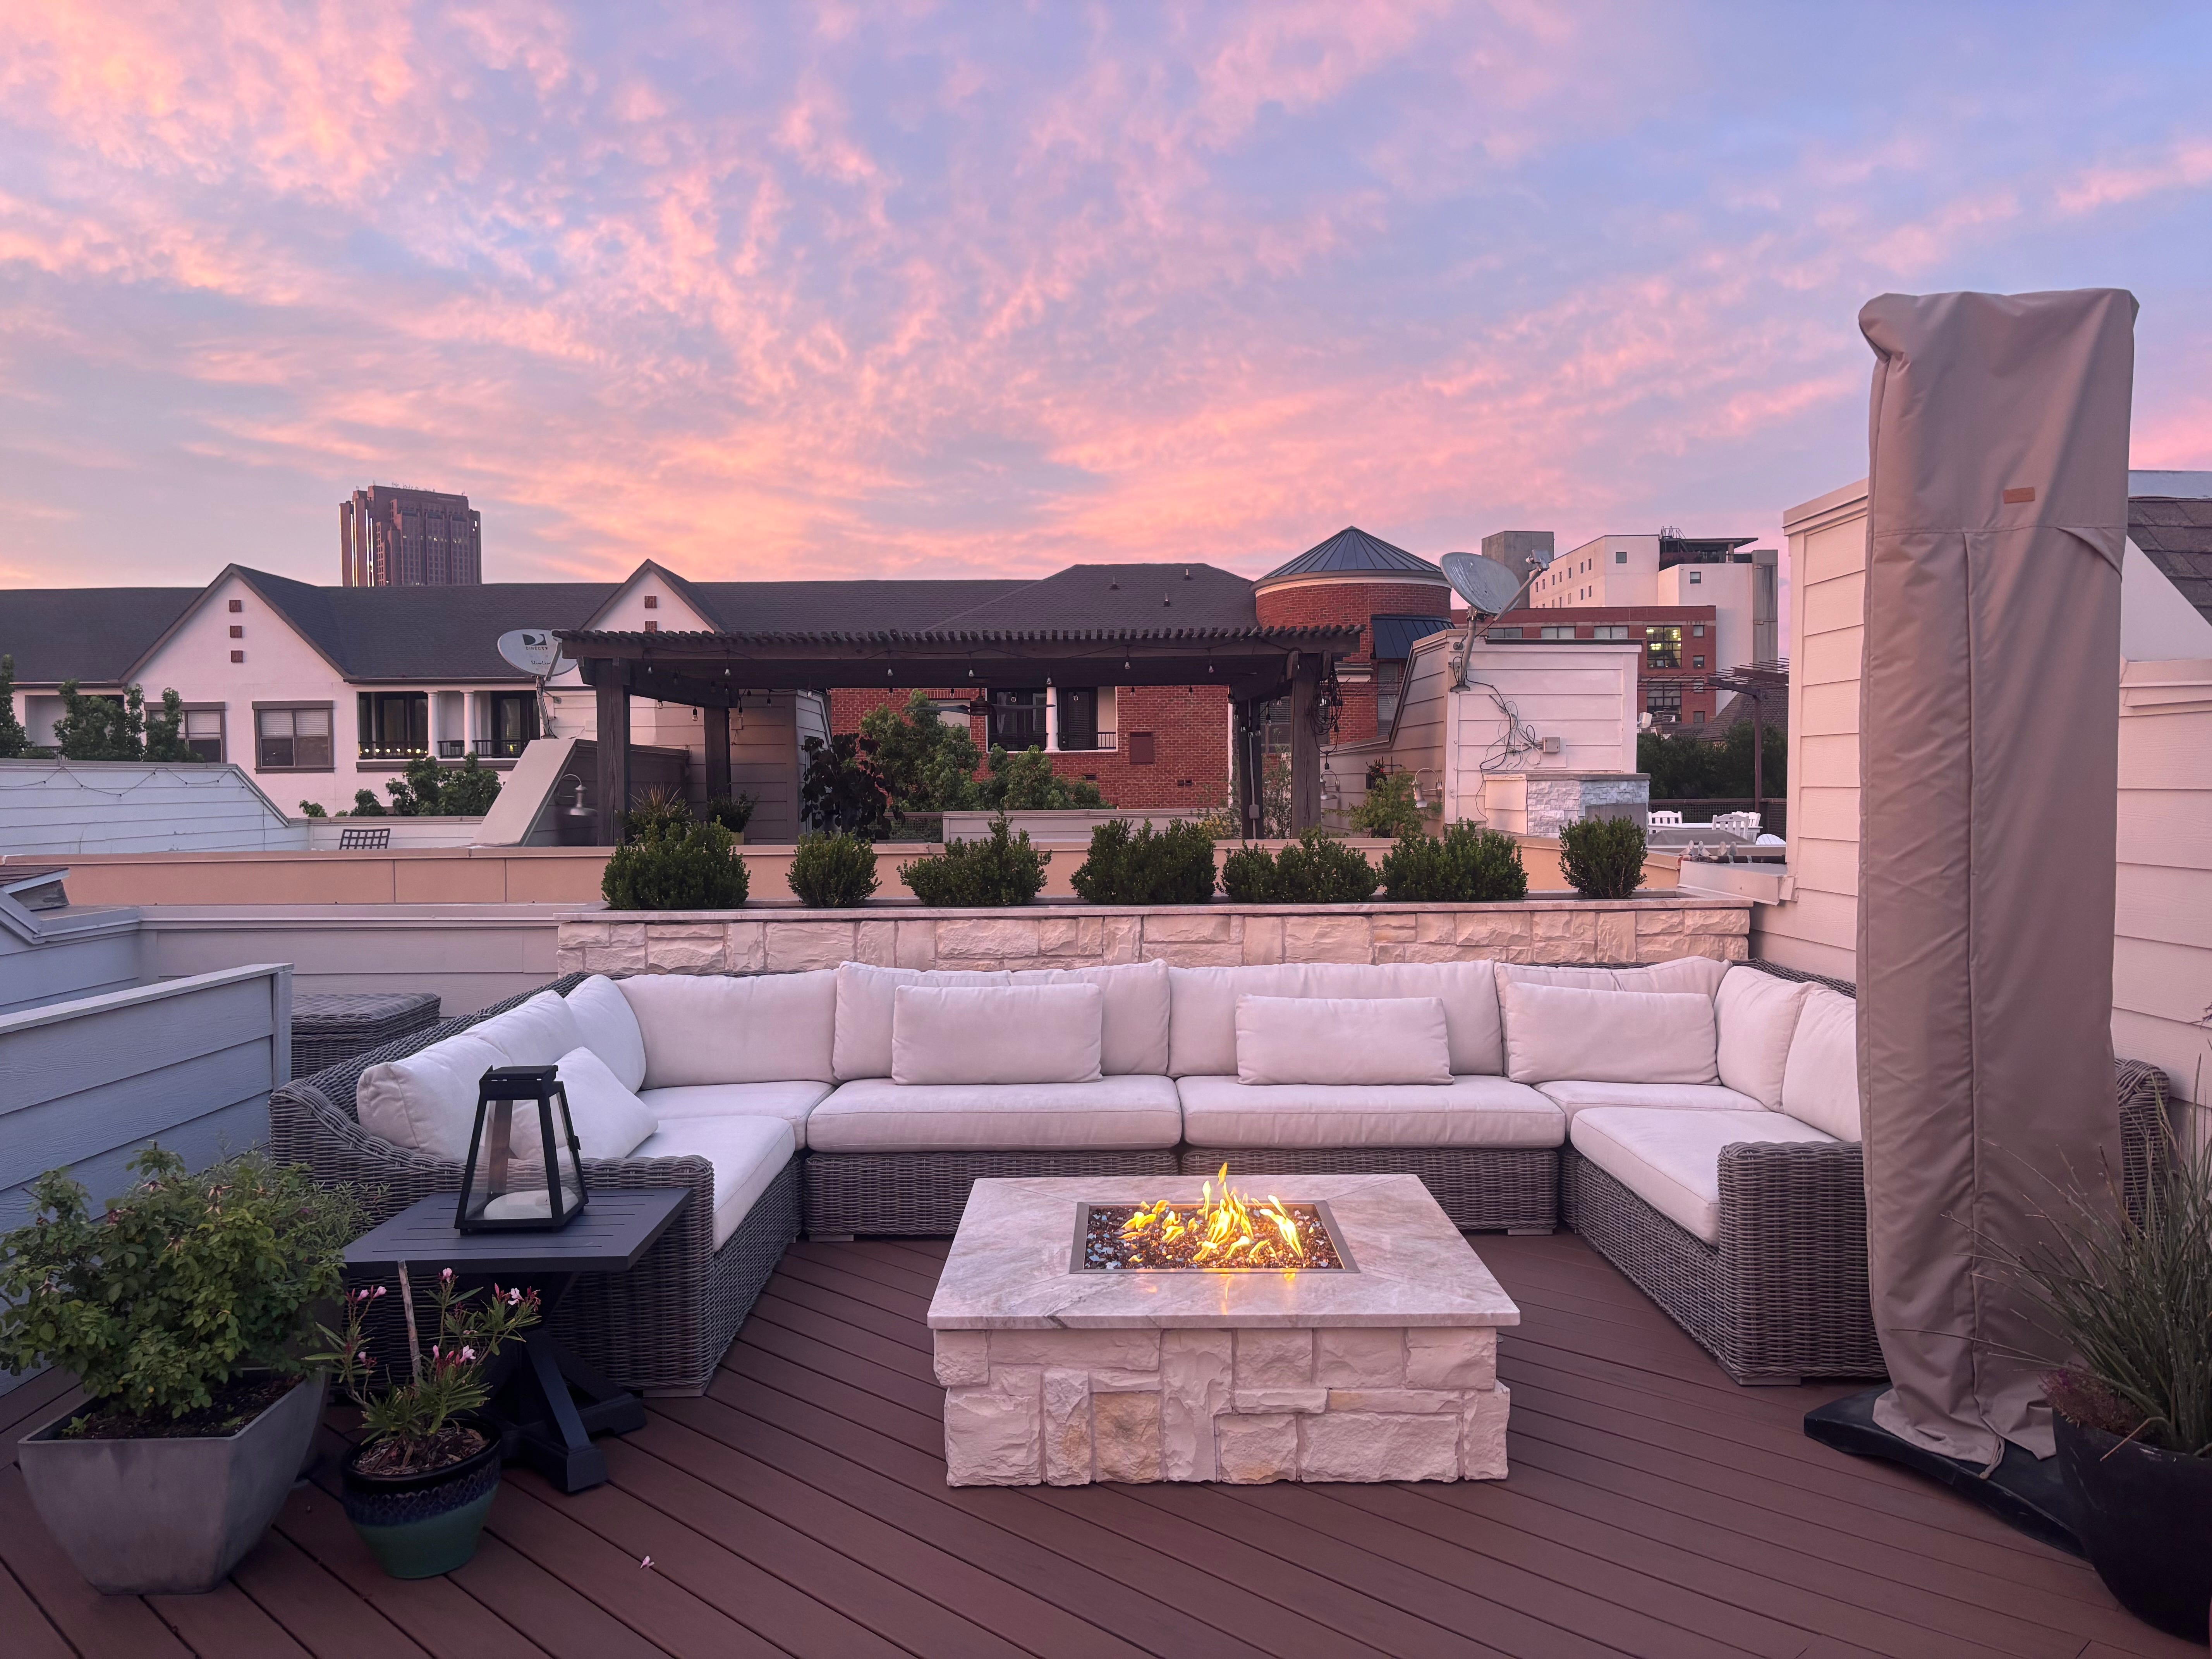
Too long clearly, since I’m starting to consider new home projects for no good reason.
Sure, my home value will likely continue to rise over time - nearly everything does if you hold long enough. But that’s not why I choose the ongoing hassle of managing, insuring, protecting, and continually improving an illiquid, depreciating asset.
I don’t stay because I love my 2.75% mortgage rate, or the fact that I can deduct my Texas-sized property tax bills.
My home is my sanctuary. I’ve decorated and renovated it to my exact tastes over many years. I know my neighbors, the pet store owners next door, and the bartenders at the wine bar around the corner.
I’ve lived in this neighborhood for over twenty years. I’ve nurtured the local trees and raised two dogs in the nearby parks. I don’t know how long I’ll stay, but it’s been a welcome anchor during a tumultuous time.
Owning a home is as much a lifestyle choice as a financial decision. It can be a great way to put down roots and have more control over your living space.
Just don’t assume it’s a magic financial bullet.
Obviously, YMMV. Appreciation is far from guaranteed and can vary widely depending on local economic forces, geographical trends and property type.
Now that more than 90% of Americans file taxes using the expanded standard deductions, the benefit of deducting mortgage interest and property taxes is nonexistent for most people - and often minimal even for those who do itemize.
The WSJ breaks down the 44% claims rejection in 2025 in The Home Insurance Coin Flip. “The risk that a claim will result in no payment among the group—State Farm, Allstate, Liberty Mutual, United Services Automobile Association and Farmers Insurance—shot up from 36% a decade earlier, according to the analysis.” [Might be paywalled]
Again, YMMV. We have been on a historic bull run that makes the stock market seem like as sure a bet as real estate did before the 2009 crash.
Calculating who comes out ahead would involve factoring in his alternative rent, the deferred maintenance I’m accumulating, and the equity I’m building via mortgage amortization. I respectfully decline to run those numbers; I wanted the house, and I have it. But women, take note: keeping the house is rarely the smartest financial move in a divorce.
I help people get organized and use wealth to design a life that feels secure and aligned. A former Wall Street banker and CERTIFIED FINANCIAL PLANNER™, I act as an unbiased advocate without selling products or managing investments. To learn more, visit my website.
DISCLAIMER: I love writing about the personal, emotional, and practical sides of money, but please remember that my Substack is strictly for educational and coaching purposes. The insights shared here are general in nature and do not constitute specific investment, tax, or legal advice. While I am a CFP® certificant, reading this does not create an official advisory relationship, and any comments or likes should not be interpreted as client testimonials. For personalized investment advice, please consult a registered financial professional.
Loved the article – the ending really got me. I rented for years and it was great… until the owner decided to sell and I had to go find a new place – and this happened more than once. Back then it was just me, so it sucked but I could deal with it. Now (with a wife, kids, schools, activities, etc...) getting forced to move would be a full-on disaster.
Honestly, the only real perk of owning for me is control. You’re not at the mercy of someone else’s plans. You can be financially independent, have no boss, live life on your own terms – but if you rent, your landlord is still kind of your boss. One decision from them and your whole setup gets flipped.
If I could sign a lease that guaranteed I could stay as long as I wanted (even with annual rent bumps tied to inflation) I’d do it immediately. Stability is the whole game – unfortunately buying is the only way to lock it in.
As far as making money, stocks/S&P500 is better than real estate in every single respect – as long as you don't do anything moronic like panic selling in a downmarket or using leverage or option instruments without understanding and accepting the risks that come along.
It is such a shame that Americans have to look at everything as a financial transaction. Housing has its financial implications-but it is an emotional transaction. Yes Condos and renting push the tasks of maintenance onto someone else-but you are still paying for it! It is the things you talk about-community, built memories, pride of ownership and the skills that go with it that makes owning worthwhile